Sungrow's financial profile is undergoing a significant transformation as the company shifts away from capital-intensive renewable project development and increasingly relies on photovoltaic inverters and energy storage systems to drive growth.
The strategic transition has helped support headline revenue expansion, with total revenue rising from RMB72.2 billion in 2023 to RMB88.9 billion in 2025. However, the changing composition of that growth has also brought higher operating costs, greater dependence on overseas markets and increased exposure to foreign exchange and working-capital risks.
The most visible change has been the contraction of Sungrow's New Energy Investment and Development business. Revenue from the segment fell from RMB24.73 billion in 2023 to RMB16.56 billion in 2025, a decline of 33% over two years. Its contribution to total revenue dropped from 34.3% to 18.6% during the same period, while gross margin fell to 14.5% in 2025 after reaching 19.4% a year earlier.
The decline reflects broader challenges facing renewable project development, including the transition away from guaranteed feed-in tariffs, electricity price volatility, grid curtailment and extended capital requirements for engineering and construction projects. Sungrow has increasingly moved toward an asset-light model centered on equipment sales, particularly energy storage systems, which accounted for 42% of revenue in 2025.
That transition has also accelerated the company's international expansion. Overseas markets contributed approximately 60.7% of group revenue in 2025, compared with 46.2% in 2023. While international markets have become an important source of growth, the expansion has required significant investment in sales infrastructure, localized services and technology development.
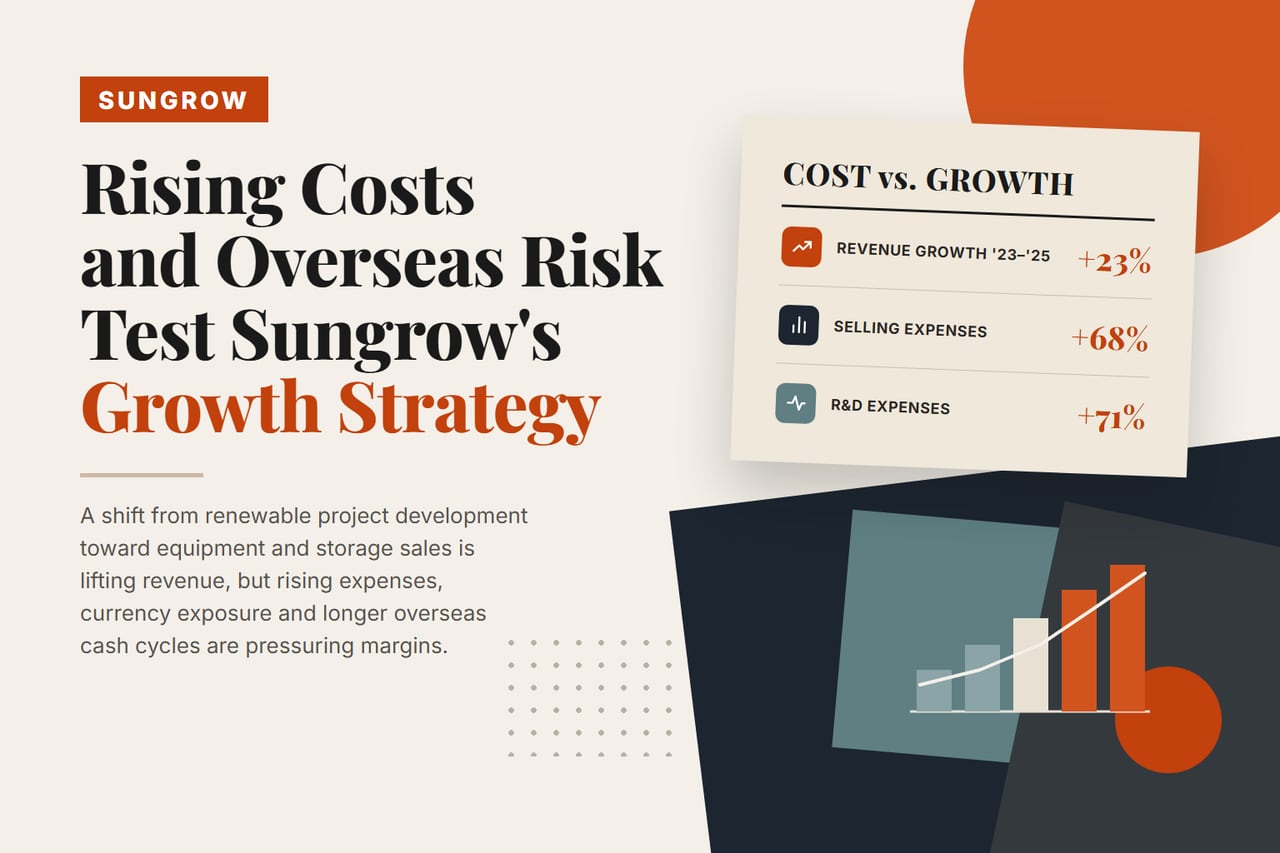
Selling expenses increased 68.3% between 2023 and 2025, while research and development expenses rose 70.6%, substantially outpacing the company's 23.2% revenue growth over the same period. Selling expenses increased from 4.0% of revenue to 5.4%, while R&D expenses rose from 3.4% to 4.7%.
The widening cost base could become increasingly important if revenue growth slows or pricing pressure intensifies in global solar and energy storage markets. Sungrow has continued investing in areas including power electronics, grid-forming technology, hydrogen systems and high-voltage DC applications, while expanding its international service network.
Customer composition has also changed significantly. Revenue generated by Sungrow's five largest customers declined from 34.4% in 2023 to 17.0% in 2025. The company's largest customer in 2023 accounted for 13% of total revenue but was no longer among the five largest customers two years later.
A more diversified customer base can reduce dependence on individual buyers, but replacing large-volume accounts across multiple international markets may also require broader sales coverage and higher customer acquisition costs.
Foreign exchange and cash conversion present another challenge. With overseas revenue exceeding RMB53.9 billion in 2025 and collection periods extending for months on major projects, the company faces greater exposure to currency movements before foreign-currency receivables are converted into cash.
Financial expenses rose sharply from RMB20.60 million in 2023 to RMB290.41 million in 2024, reflecting declining foreign exchange gains and higher overseas financing costs.
For investors, the broader question is whether Sungrow can maintain profitability as its business becomes increasingly international and operationally complex. The company's transition toward equipment and energy storage sales may reduce the capital intensity of project ownership, but rising costs, fragmented customer relationships and longer overseas cash cycles could become increasingly important tests of the sustainability and quality of future growth.
Intelligence Takeaway
The signal is less about a single headline and more about how decision-makers should read the operating environment: commercial claims, policy exposure, and execution evidence now need to be evaluated together.